Crypto in Kenya: Adoption, Payments, Stablecoins and the Market in 2026
Kenya is one of Africa’s most active cryptocurrency markets. Explore the latest data on crypto adoption, P2P trading, stablecoins, mobile money, cross-border payments and the regulatory changes shaping the market in 2026.

On this page
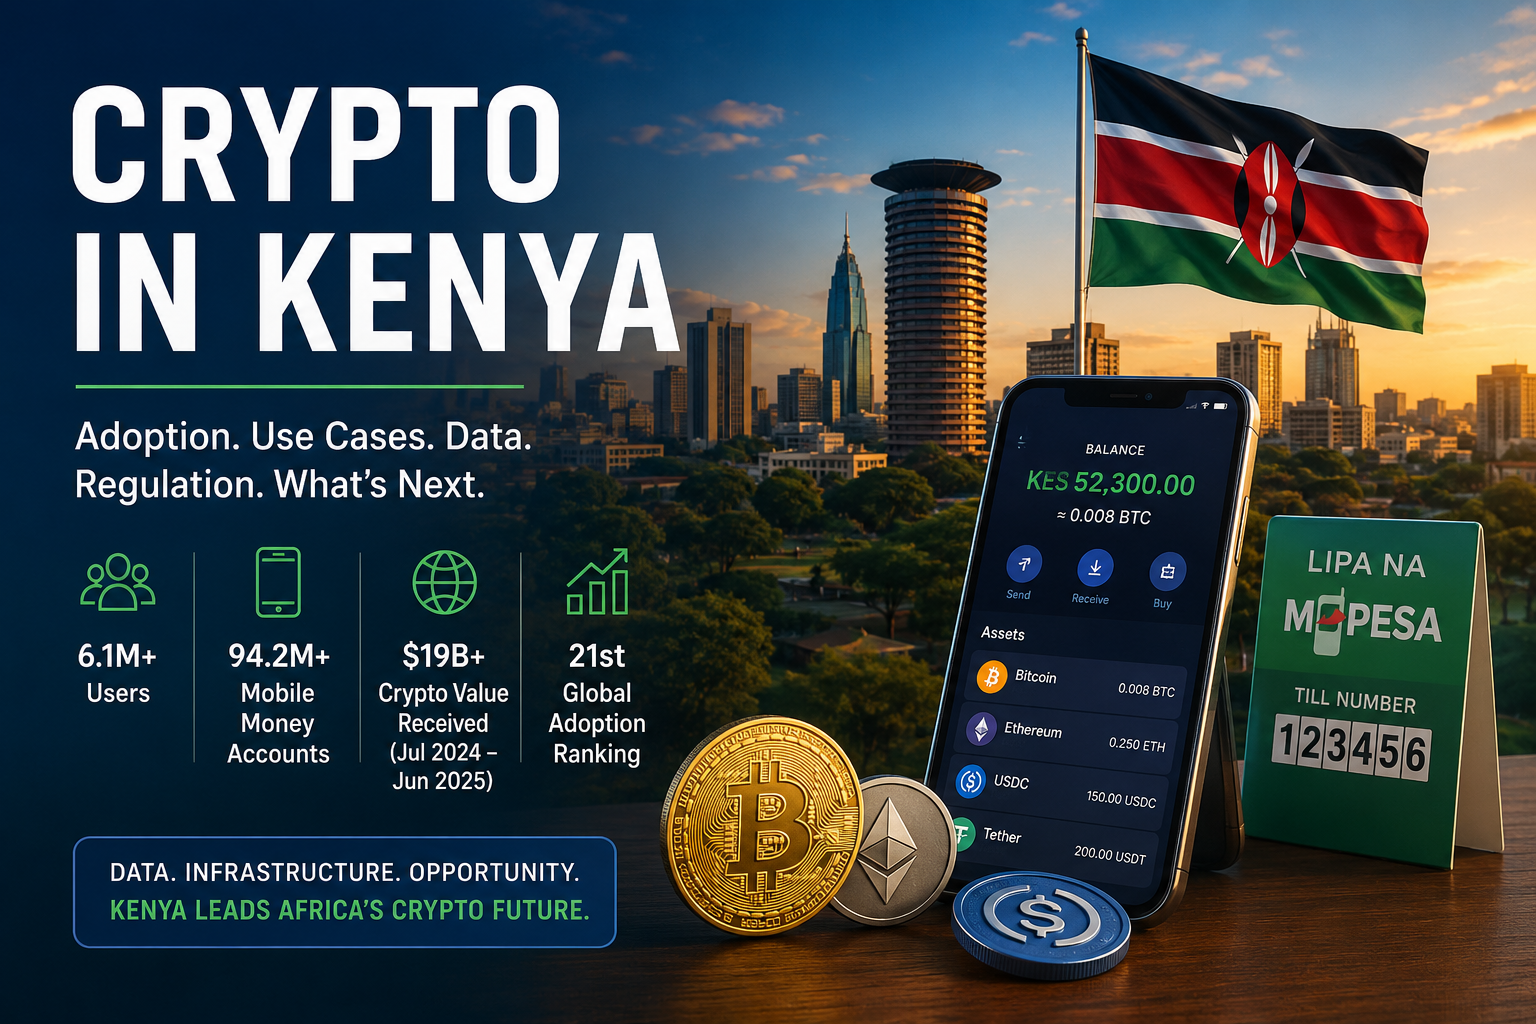
Kenya received more than USD19 billion in cryptocurrency value between July 2024 and June 2025, according to Chainalysis data cited by Business Daily.
Kenya ranked 21st globally in the 2025 Global Crypto Adoption Index, putting the country among Africa’s most active cryptocurrency markets.
The market is also entering a new regulatory phase. Kenya’s Virtual Asset Service Providers Act took effect in November 2025, and the final VASP Regulations were gazetted in July 2026.
Now, let us look at how cryptocurrency is actually used in Kenya.
We will look at adoption, peer-to-peer trading, mobile money, stablecoins, cross-border payments, regulation, risks and the market’s direction in 2026.
Kenya Is Already a Significant Crypto Market
Kenya’s adoption ranking is not simply a measure of interest in Bitcoin. Chainalysis combines several types of activity, including centralized services, retail activity, DeFi and institutional transfers.
Its methodology is designed to identify where cryptocurrency is being used at grassroots level.
Sub-Saharan Africa received more than USD 205 billion in on-chain value between July 2024 and June 2025, about 52 percent more than the previous year. Kenya was among the region’s leading markets.
The size of Kenya’s market is therefore difficult to explain through speculation alone. Crypto has found use in payments, transfers, savings and access to dollar-denominated assets, alongside conventional investment activity.
How Many Kenyans Own Cryptocurrency?
Kenya has an estimated 6.1 million cryptocurrency users. Molo MP Kuria Kimani cited the figure during a June 2025 debate on the Virtual Asset Service Providers Bill in the National Assembly.
The figure is also close to Triple-A's estimate of 6.1 million cryptocurrency owners, equivalent to 10.71 percent of Kenya's population. The two figures come from different sources. They should not be treated as identical datasets.
Peer-to-Peer Trading Has Been Important in Kenya
Peer-to-peer trading has played an unusually important role in Kenya.
An IMF technical assistance report noted earlier research estimating that Kenya accounted for more than 12 percent of Africa’s peer-to-peer Bitcoin trades.
P2P trading lets users deal directly with buyers and sellers.
It does not always require a conventional exchange. In Kenya, this model grew alongside widespread mobile-money use and digital transfers.
The model also creates risks. P2P markets can expose users to fraud, payment reversals, identity risks and counterparties whose source of funds is difficult to establish.
That is one reason formalisation has become important.
Mobile Money Gives Crypto a Different Starting Point
Kenya’s cryptocurrency market is built on top of a mature mobile-money system. The country’s digital-payment habits were established long before crypto became mainstream.
By June 2026, Kenya had 94.2 million registered mobile-money accounts.
It also had 572,104 active agents.
Agent cash-in and cash-out transactions totalled 212.45 million during the month, with a combined value of KSh682.46 billion.
Those are not cryptocurrency figures. They show why Kenya can support digital-asset products that connect blockchain-based value with familiar local payment rails.
For a Kenyan user, the important part of a crypto transaction may not be the blockchain itself. It may be how easily digital value can be converted into shillings, sent to a mobile wallet or used to pay someone abroad.
- You can use mobile money like M-pesa to buy bitcoin in Kenya here.
Why Stablecoins Matter in Kenya
Stablecoins are designed to maintain a relatively stable value, often against the US dollar. That makes them different from volatile assets such as Bitcoin.
For Kenyan users, the dollar link can be useful. A stablecoin can provide digital access to dollar-denominated value without requiring physical dollars. It can also be transferred between wallets and across borders.
Chainalysis says stablecoins are frequently involved in high-value transactions. These transactions are linked to trade flows between Africa, the Middle East and Asia, including multi-million-dollar transfers associated with energy and merchant payments.
That does not mean stablecoins have replaced banks or mobile money in Kenya. Their role is better understood as an additional settlement and value-transfer layer.
Crypto and Cross-Border Payments
Kenya’s large cross-border payments market creates a natural use case for digital assets. CBK reported USD436.6 million in diaspora remittance inflows in July 2026. The 12-month total to July was about USD4.987 billion.
A separate 2025 Remittances Household Survey estimated KSh931.8 billion in household remittance inflows between June 2024 and May 2025. Banks and mobile-money platforms accounted for more than 92 percent of those inflows.
Crypto is only one part of this market. Digital assets can provide another route for moving value internationally, particularly where users need dollar-linked liquidity or want to reduce the number of intermediaries.
Business Daily has reported that Kenyan firms have used crypto for foreign supplier payments, with dollar shortages and shilling depreciation contributing to interest in alternative settlement methods.
What Is Driving Crypto Adoption in Kenya?
- 1Mobile-first financial behaviour. Kenyans are accustomed to sending and receiving money digitally.
- 2Cross-border payment needs. Businesses, freelancers and households regularly move money across borders.
- 3Access to dollar-linked value. Stablecoins provide another route to digital dollar exposure.
- 4Peer-to-peer markets. P2P trading developed as an accessible route into crypto.
- 5Entrepreneurship. Kenya’s fintech ecosystem has created a base of developers and businesses comfortable with digital financial products.
None of these factors alone explains the market. Together, they help explain why crypto has found practical use alongside speculative trading.
Crypto Use Is Not the Same as Crypto Payments
It is important to separate ownership, trading and payments. A country can have high cryptocurrency adoption without people routinely buying groceries with Bitcoin.
The IMF’s assessment of Kenya found that direct use of crypto assets for domestic purchases of non-financial goods and services appeared limited. It also noted that no crypto-asset ATMs were known to be operating in Kenya at the time of its assessment.
Kenya can therefore be a major crypto market.People trade, save, transfer and convert digital assets even while everyday retail payments remain dominated by shillings and mobile money.
Kenya’s Regulatory Shift Changes the Market
Kenya’s regulatory position changed materially between 2025 and 2026. The VASP Act created the legal foundation for regulating virtual-asset service providers, while the final 2026 regulations established the framework for licensing and supervision.
The change affects how exchanges, wallet businesses, payment providers and other crypto companies structure their: - Operations - Compliance - Systems - Relationships with financial institutions.
For the detailed licence categories, capital requirements, liquid-capital rules and transition requirements, see Finlazo’s comprehensive analysis of Kenya’s VASP regulations.
The broader market is now moving from regulatory uncertainty toward a defined supervisory regime. That can increase confidence for some businesses while raising the cost and complexity of operating for others.
Regulation Could Change Who Builds in Kenya
The new framework creates a test for Kenya’s crypto industry. Larger companies may be better positioned to absorb compliance, technology and governance costs. Smaller startups may face a harder path to market.
Business Daily reported in August 2026 that some Kenyan crypto startup founders were considering South Africa and Mauritius if they could not meet the requirements before the transition deadline.
That does not mean Kenya will lose its crypto industry. Regulatory clarity can also attract institutional capital and make partnerships easier for businesses that meet the rules.
The Risks Are Real
Crypto adoption creates opportunities, but it also creates financial and operational risks.
Price volatility remains the most obvious. Bitcoin and other non-stablecoin assets can move sharply within short periods.
Fraud is another concern. P2P transactions, fake investment schemes, impersonation and account takeovers can cause losses that are difficult to recover.
Stablecoins carry a different set of risks. Users depend on the issuer’s reserves, redemption mechanisms, technology and regulatory arrangements.
Cross-border transactions also create compliance challenges. Customer identification, sanctions screening, transaction monitoring and source-of-funds checks can become more complicated when value crosses jurisdictions.
What Kenya Needs From the Next Phase of Crypto Growth
The next stage is likely to be less about proving that people will use digital assets. It will be more about deciding where those assets fit inside the financial system.
The strongest opportunities may sit at the intersection of existing infrastructure and blockchain-based settlement. Mobile money can provide local access. Banks can provide regulated financial services. Exchanges can provide conversion. Stablecoins can provide digital dollar liquidity.
That model is more practical than treating cryptocurrency as a replacement for Kenya’s existing financial system. The larger opportunity is connecting local payment infrastructure to global digital-asset liquidity without weakening consumer protection.
Kenya’s Crypto Market in Numbers
- 21st — Kenya’s position in the 2025 Chainalysis Global Crypto Adoption Index
- USD19 billion+ — cryptocurrency value received by Kenya between July 2024 and June 2025
- 6.1 million — estimated Kenyan cryptocurrency owners in Triple-A’s dataset
- 10.71% — estimated population share in Triple-A’s dataset
- USD436.6 million — July 2026 diaspora remittance inflows
- USD4.987 billion — 12-month remittances to July 2026
- 94.2 million — registered mobile-money accounts in June 2026
- KSh682.46 billion — June 2026 mobile-money agent cash-in/cash-out value
- USD205 billion+ — Sub-Saharan Africa on-chain value received from July 2024 to June 2025
- 52% — year-on-year growth in Sub-Saharan Africa on-chain value received




