Kenya’s Crypto Startups Face a Race Against Time as KSh100 Million Exchange Rule Looms
Kenya’s new crypto rules set capital requirements as high as KSh300 million, putting startups under pressure ahead of the November 4, 2026 compliance deadline.

On this page
Kenya’s new cryptocurrency regulations are putting local startups on a race against time.
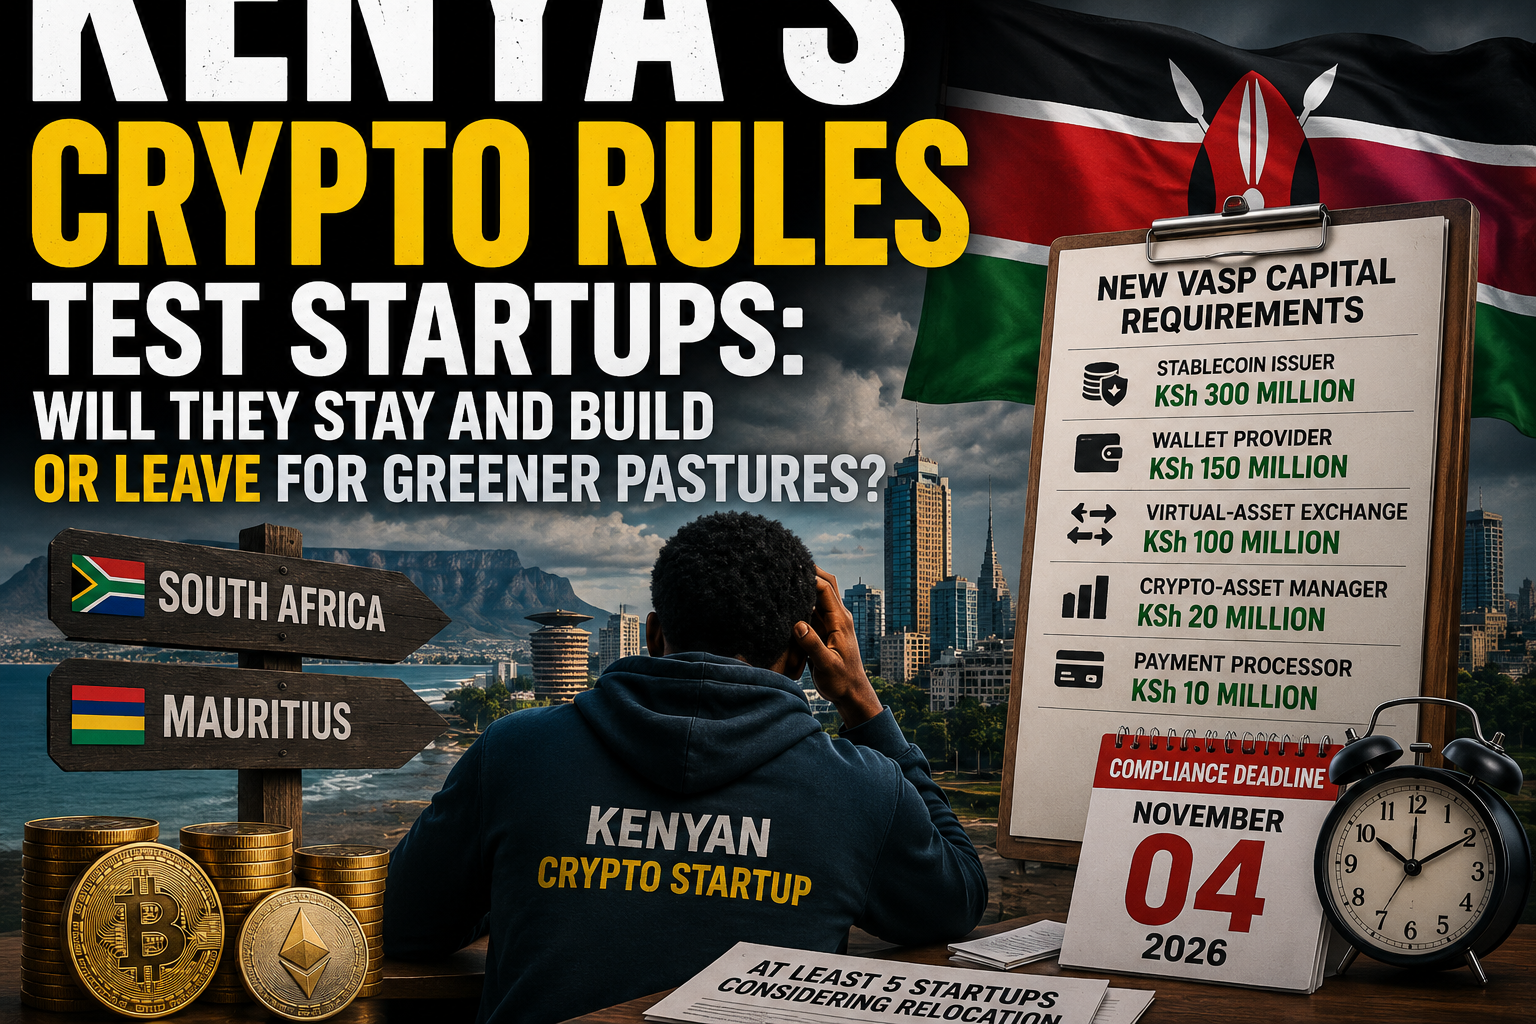
At least five founders are considering South Africa or Mauritius if they cannot raise the required capital before the November 4, 2026 deadline. A virtual-asset exchange now requires KSh100 million in paid-up capital, while stablecoin issuers face a KSh300 million threshold and wallet providers KSh150 million.
The rules come as Kenya remains one of Africa’s most active cryptocurrency markets.
Kenya ranked 21st globally in Chainalysis’ 2025 Global Crypto Adoption Index, up from 28th in 2024, and fourth in Africa behind Nigeria, Ethiopia and South Africa.
The result is a difficult policy question: can Kenya build a safer, better-capitalized virtual-asset industry without making it too expensive for the startups that helped build the market in the first place?
November 4 Is the Deadline Startups Cannot Ignore
The Virtual Asset Service Providers Act, 2025 came into force on November 4, 2025. Existing operators were given a one-year transition period to move into the new licensing framework, making November 4, 2026 the key compliance deadline for businesses already serving the Kenyan market.
The final Virtual Asset Service Providers Regulations, 2026 were gazetted in July and now provide the detailed rules governing licensing, capital, governance, market conduct, consumer protection and other requirements.
For startups, the deadline is not simply an administrative date. A company that has already built a product and attracted users must now decide whether it can raise the required funds, satisfy the relevant regulator and complete the transition in time.
The Capital Requirements Are High — But They Are Not the Same for Everyone
Kenya’s final framework uses different capital thresholds for different virtual-asset activities.
The amounts reflect the type of business being licensed rather than imposing one blanket figure across the sector.
Key minimum paid-up capital requirements under the final framework:
- 1KSh300 million — stablecoin issuers
- 2KSh150 million — virtual-asset wallet providers
- 3KSh100 million — virtual-asset exchanges
- 4KSh20 million — virtual-asset managers
- 5KSh10 million — virtual-asset payment processors and brokers
These thresholds are separate from other regulatory costs and liquidity requirements.
The regulations also require certain categories to maintain liquid capital based on liabilities. That is creating an additional financial-resilience requirement beyond the money shareholders initially contribute.
The Stablecoin Threshold Was Cut by 40 Percent — But It Remains the Highest
The final KSh300 million stablecoin-issuer requirement is already a significant reduction from the KSh500 million threshold proposed in the March 2026 draft regulations.
That represents a 40 percent reduction following industry consultation.
The final rules also set liquid-capital requirements.
A stablecoin issuer must maintain at least KSh60 million or an amount equal to 100 percent of current liabilities for at least 30 days, whichever is higher. An exchange must maintain KSh20 million or 8 percent of total liabilities, whichever is higher.
The distinction matters. That is because stablecoin issuers are not simply trading existing assets.
Their activities can involve reserves, redemption and direct interaction between digital tokens and fiat value, giving regulators a reason to apply a higher prudential threshold.
For a comprehensive, step-by-step breakdown of application fees, liquid capital buffers, and licensing steps, read our definitive master guide to Kenya Cryptocurrency Regulation 2026
At Least Five Startups Are Looking Beyond Kenya
The clearest sign of industry concern came from the founders themselves. Business Daily reported that at least five Kenyan cryptocurrency startup founders were considering registering their businesses in South Africa or Mauritius if they could not raise the required capital before November 4.
Eric Michubu, founder of Taran App, said his company would need KSh100 million to qualify for a virtual-asset exchange licence. Taran allows users to exchange stablecoins and other virtual assets for local currencies in East Africa.
The difficulty is not necessarily that the founders reject regulation. The concern is that a fixed capital requirement can arrive before a young company has reached the scale at which institutional investors are willing to commit large sums.
For an early-stage fintech, that creates a difficult sequence: investors may want regulatory certainty before investing. And the company may need the investment to satisfy the capital requirement needed to obtain regulatory certainty.
Tando Shows Why the Issue Is Wider Than Exchanges
The pressure is not limited to large exchanges. Business Daily reported that Tando, a startup that enables users to make Bitcoin-funded payments into M-Pesa personal and merchant accounts, faces a KSh10 million capital requirement. It is a virtual-asset payment processor.
For smaller payment businesses, the issue is the relationship between regulatory capital and actual business scale. A company can have a working product and customers. But it can lack tens of millions of shillings as available paid-up capital.
Industry participants have called for a more flexible approach. They argue that regulation should consider a company's size, business model and stage of development. The goal is to protect customers without making the market accessible only to heavily funded companies.
Kenya Is Regulating a Market That Is Already Significant
The capital debate is taking place against a backdrop of strong crypto activity. Kenya’s position in Chainalysis’ 2025 adoption index improved from 28th globally in 2024 to 21st in 2025, placing the country fourth in Africa.
At the regional level, Sub-Saharan Africa’s on-chain crypto activity grew by 52 percent year-on-year in the 12 months ending June 2025, according to Chainalysis. The region received more than $205 billion in on-chain value during the period, with crypto continuing to be used for remittances, payments and other everyday financial needs.
That growth explains why regulators are moving toward formal supervision. The question is no longer whether virtual assets exist in Kenya. They do. The question is what kind of regulated industry Kenya wants to build around them.
The Government Also Removed a Proposed 33.3 Percent Ownership Cap
Capital requirements were not the only part of the framework that changed during the transition from draft to final regulations.
National Treasury removed a proposed rule that would have prevented any individual or entity from controlling more than 33.3 percent of an exchange, stablecoin issuer or wallet provider.
The proposed restriction would have covered issued share capital, voting rights, board representation, dividends and shareholder-loan interests. Its removal gives founders, venture capital investors and strategic investors greater flexibility to take controlling positions in licensed virtual-asset businesses.
The final framework also reduced the initial licence fee for virtual-asset exchanges from the proposed KSh2 million to KSh1 million, while the annual renewal fee was set at KSh500,000 or 0.5 percent of the previous year’s gross revenue, whichever is higher.
South Africa and Mauritius Are Now Part of Kenya’s Competitive Equation
The possibility of relocation matters because Kenyan crypto startups have alternatives. Business Daily reported that South Africa does not prescribe one fixed capital requirement for every crypto-asset service provider.
Instead, applicants are assessed on whether they have adequate financial resources for the nature and scale of their operations.
Mauritius has fixed capital requirements for some virtual-asset activities, but the reported thresholds are lower in several categories. An exchange requires roughly KSh18 million, a broker about KSh5.5 million and a virtual-asset custodian about KSh14 million. Some other categories do not have a fixed minimum and instead require sufficient working capital.
The comparison does not mean South Africa or Mauritius are automatically easier jurisdictions. Each has its own licensing, tax, governance and compliance requirements, with South Africa's crypto regulation commencing in October 2022.
But for a startup deciding where to establish its regional base, the amount of capital that must be committed before it can operate is an important part of that calculation.
The Case for Stronger Capital Requirements
There is a straightforward argument for requiring virtual-asset companies to have meaningful financial resources.
Crypto businesses can face custody failures, cybersecurity incidents, liquidity problems, operational losses and sharp market movements. A well-capitalised company is better positioned to absorb losses and maintain critical operations.
Capital requirements can also discourage weak operators from entering the market simply to take advantage of a fast-growing sector.
For customers, a regulated company with sufficient financial resources can provide a stronger level of protection than an undercapitalised operator.
From the regulator’s perspective, the goal is therefore not simply to make entry difficult. It is to ensure that firms entrusted with customer assets or important financial functions have the capacity to operate responsibly.
The Case for a More Flexible Approach
The counterargument is that early-stage companies do not carry the same scale of risk as large exchanges or stablecoin issuers. A startup with a small customer base may be required to lock up substantial capital before it has the revenue needed to support a large compliance operation.
Fixed thresholds can also favour incumbent financial institutions and well-funded foreign companies over Kenyan founders.
A large bank or multinational fintech may be able to absorb a KSh100 million requirement more easily than a local startup that has raised only a few million shillings but has developed useful technology.
That is why the debate is increasingly about calibration rather than regulation versus no regulation. Kenya needs rules that protect consumers and the financial system. But the rules also need to leave room for companies to grow into larger, more resilient businesses.
What the November Deadline Could Change
The November 4 deadline could reshape the composition of Kenya’s crypto industry.
Some startups will raise capital and obtain licences. Others could merge with better-capitalised companies, restructure their products to fit different licence categories or seek a base in another African jurisdiction.
The result could be a smaller and more financially resilient industry. But imagine if early-stage businesses decide that the cost of entering Kenya is higher than the cost of building elsewhere. It could mean fewer locally founded companies.
For policymakers, that makes the implementation phase as important as the regulations themselves. Consistent licensing, clear regulatory guidance and predictable supervision could help reduce uncertainty for investors and founders.
For startups, the message is equally clear: the era of operating around regulatory uncertainty is ending. By November 4 2026, businesses serving Kenyan customers will need to know exactly where they fit within the framework and whether they have the financial capacity to remain in the market.
Kenya’s Bigger Opportunity
Kenya has spent more than a decade building a reputation as one of Africa’s leading digital-finance markets. Its mobile-money infrastructure, fintech ecosystem and growing use of digital assets give it a strong base from which to develop a regulated virtual-asset industry.
The opportunity is to turn that market activity into an industry that can attract institutional capital, protect consumers and develop products that serve both Kenya and the wider African market.
The risk is that regulation becomes so expensive or inflexible that the next generation of Kenyan builders chooses to develop those products elsewhere. The November 4 2026 deadline will therefore be more than a compliance milestone.
It will be an early test of whether Kenya can strengthen its crypto industry without weakening the entrepreneurial ecosystem that helped make the country one of Africa’s most important digital-finance markets.




