PayShap vs Stablecoins: Which Actually Moves Money Faster in South Africa 2026?
PayShap can move ZAR between South African bank accounts in seconds. Stablecoins can settle quickly too. Here is where each payment rail actually wins

On this page
PayShap can put money into a recipient's South African bank account in seconds. Absa says a successful PayShap payment reflects in less than 10 seconds, while Capitec says payments usually reflect within a few seconds and the service operates 24 hours a day, seven days a week, according to Absa and Capitec.
PayShap recorded 329 million transactions worth R292.5 billion by the end of its 2025 reporting period, according to PayInc.
Stablecoins can also move extremely quickly.
Circle says some supported USDC transfer routes can complete in about 8 seconds, while timing depends on the blockchain and transfer method. Its documentation lists a typical standard completion time of about 25 seconds for certain transfers to Solana, according to Circle.
Stablecoins are growing from a very different base. The SARB says they account for the bulk of transactional activity on South African crypto exchanges, but says most of that activity is tied to trading, arbitrage and settlement within crypto markets rather than payments for goods and services.
But the headline comparison is misleading if it ends there.
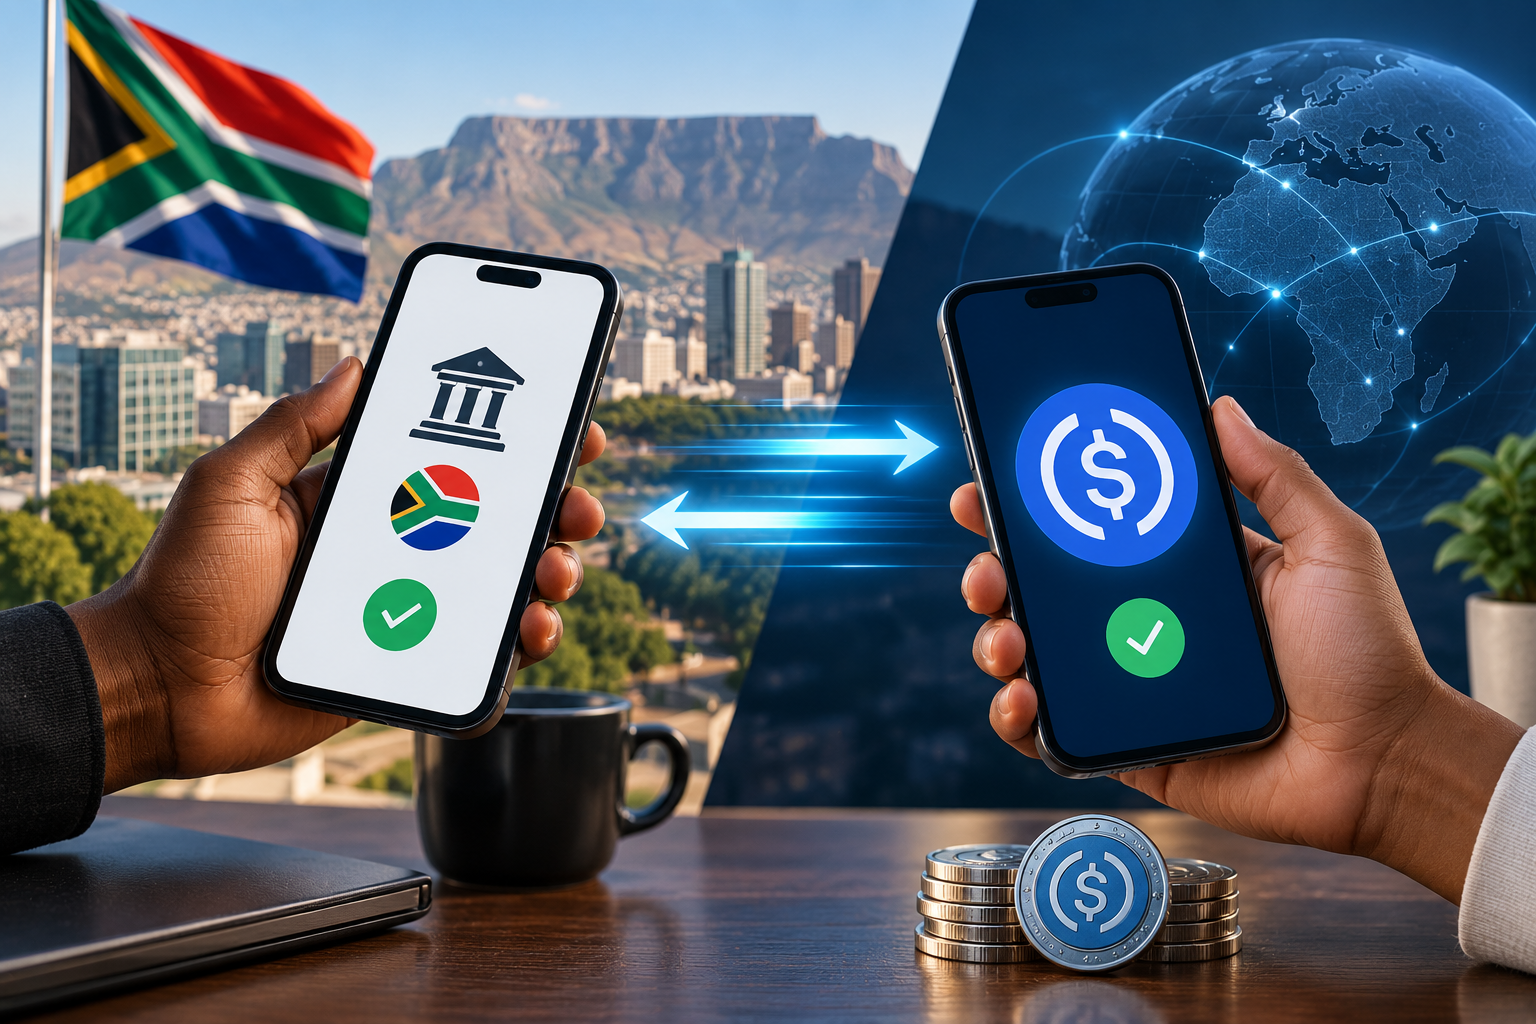
For an ordinary domestic payment between two South African bank accounts, PayShap is usually faster in practical terms because the money arrives directly as usable rand.
For moving value between blockchain wallets, particularly across borders, stablecoins can have a major speed advantage because they are not confined to one country's banking rails.
The real contest is not seconds against seconds.
It is end-to-end usable money.
The short answer
If you want to send rand from one South African bank account to another, PayShap wins the practical speed test.
There is no crypto asset to buy.
There is no blockchain wallet to fund.
There is no off-ramp.
The recipient receives ZAR directly.
If you want to move value from one blockchain wallet to another, stablecoins can move extremely quickly.
But if the sender starts with rand and the recipient ultimately needs rand in a bank account, buying the stablecoin and converting it back can add steps.
Those extra steps can erase the theoretical advantage of blockchain settlement.
What PayShap actually does
PayShap is South Africa's faster retail payment system.
The South African Reserve Bank says the country has been working with the private sector to improve gaps in fast retail payments. In a 2026 speech, SARB Deputy Governor Rashad Cassim said South Africa's retail system had not previously been as quick, cheap or continuously available as some major fast-payment markets, according to the SARB.
PayShap launched in March 2023 as a low-value, real-time retail payment platform, according to the SARB's Digital Payments Roadmap.
The important feature is not only speed.
It is where the payment lands.
A PayShap transaction moves money from a payer's bank account into the recipient's bank account.
The recipient does not need to convert anything after receiving the funds.
PayShap timing in practice
Absa says successful PayShap payments reflect instantly in less than 10 seconds, according to Absa's PayShap FAQ.
Capitec says PayShap operates 24/7, including weekends and public holidays, and that payments usually reflect within a few seconds, according to Capitec.
Standard Bank says PayShap funds are paid into the recipient's bank account within minutes and that customers can transact 24/7, according to Standard Bank.
Those descriptions show why there is no single universal PayShap timing.
The customer experience can depend on the participating bank and payment flow.
But PayShap is built for immediate domestic bank-to-bank payments.
Stablecoins can be faster at the settlement layer
Stablecoins are different.
They are not one payment rail.
Their speed depends on the asset, blockchain, wallet infrastructure and route.
USDC, for example, operates across multiple blockchain networks.
Circle says some Fast Transfer routes can complete in about 8 seconds, while its standard transfer timing to Solana is typically about 25 seconds, according to Circle's transfer documentation.
Circle also says timing varies because different blockchains reach transaction finality at different speeds.
Its Gateway infrastructure separately advertises USDC transfers in under 500 milliseconds after a balance has already been established within that specific system, according to Circle Gateway.
That is not a general promise that every stablecoin payment reaches every recipient in under 500 milliseconds.
It is an infrastructure-specific performance claim.
This is why saying “stablecoins are always faster than PayShap” would be wrong.
A blockchain transfer can be extremely fast.
Blockchain settlement is only one part of the payment journey.
The real race is end-to-end
Imagine two people in Johannesburg.
The sender has rand.
The recipient wants rand.
Route A: PayShap
The sender opens a banking app.
The sender uses the recipient's ShapID or other supported details.
The payment is authorised.
The recipient receives ZAR directly.
At Absa, the published timing for a successful payment is less than 10 seconds, according to Absa.
There is no separate asset conversion.
Route B: Stablecoin
The sender may first need to buy USDC.
The USDC is transferred on a chosen blockchain.
The recipient receives USDC.
If the recipient needs rand, the USDC must then be converted and paid out into a bank account or another spendable payment instrument.
The blockchain leg might be faster than 10 seconds on some routes, according to Circle.
The full journey may not be.
Fast settlement does not automatically mean fast usable money.
PayShap wins for ordinary domestic ZAR payments
For a domestic person-to-person payment, PayShap has a structural advantage.
The sender holds ZAR.
The recipient receives ZAR.
The transaction stays inside the domestic payment system.
No exchange rate is involved.
No crypto conversion is required.
No wallet address needs to be managed.
The SARB's Payments Ecosystem Modernisation Programme says the objective includes fast, secure and affordable digital payment options through PayShap and future regional immediate-payment infrastructure.
For splitting rent, repaying a friend or moving money between South African bank accounts, PayShap is difficult to beat on simplicity plus speed.
Stablecoins have a different advantage: cross-border movement
The stablecoin case becomes stronger when money needs to leave South Africa.
PayShap is a domestic payment rail.
A stablecoin such as USDC can move between compatible blockchain wallets across national borders.
The SARB itself recognises this distinction. In a 2026 speech, the central bank said stablecoins account for the bulk of transactional activity on South African crypto exchanges, although most of that activity is related to trading, arbitrage and settlement within crypto markets rather than everyday payments. The SARB said stablecoins are also used to a lesser extent for cross-border transfers and remittances, according to the SARB's July 2026 speech.
If both parties already hold and can use the stablecoin, the transfer can be direct.
If the recipient needs local fiat, the off-ramp can become the slowest part.
The biggest stablecoin advantage is settlement across borders
Traditional cross-border transfers can involve correspondent banks, operating cut-offs, currency conversion and compliance reviews.
A stablecoin transfer can reduce the number of settlement layers between two wallets.
That is why stablecoins are attracting attention in cross-border payments.
But speed does not remove regulatory obligations.
In May 2026, South African regulators issued a joint communication on crypto assets for domestic payment purposes. The communication said the SARB is unlikely to consider foreign-currency-pegged stablecoins as payment instruments for domestic transactions because of concerns including currency substitution. The authorities are continuing to analyse rand-pegged stablecoin use cases, according to the Joint Communication.
That matters for this comparison.
USDC should not be presented as a simple domestic replacement for PayShap.
The two systems solve different problems.
What about fees?
Speed is not the only variable.
PayShap fees and transaction limits can vary by bank.
Absa currently allows up to R3,000 per ordinary PayShap payment through its listed channels, subject to individual account or profile limits, according to
Stablecoin costs can include an on-ramp fee, exchange spread, blockchain network fee, withdrawal fee and off-ramp fee.
The blockchain transaction itself may be cheap.
The full journey from ZAR to USDC and back to ZAR can cost more.
The fastest-looking rail on paper is therefore not always the fastest or cheapest end-to-end route.
A simple speed test
Sending R1,000 from one South African bank account to another
Winner: PayShap.
The recipient gets ZAR directly.
There is no crypto conversion.
At Absa, a successful payment is published as reflecting in less than 10 seconds, according to Absa.
Sending USDC from one compatible wallet to another
Winner: Stablecoin infrastructure.
PayShap cannot send a bank payment directly to a blockchain wallet.
USDC can move directly between compatible wallets. Circle says some supported Fast Transfer routes can complete in about 8 seconds, while other routes take longer, according to Circle.
Sending value from South Africa to another country
Potential winner: Stablecoins for settlement speed.
But the full payout route decides the real result.
If the recipient needs local fiat, conversion, compliance and payout availability can determine the final delivery time.
Paying for ordinary goods in South Africa
Winner today: domestic ZAR payment infrastructure.
PayShap delivers rand directly into the local financial system.
South African regulators have also made clear that foreign-currency-pegged stablecoins face a different policy question when proposed as domestic payment instruments, according to the May 2026 Joint Communication.
Which one is actually faster?
For domestic South African payments, PayShap is usually faster where it matters most: the recipient receives usable rand directly.
For direct wallet-to-wallet transfers, stablecoins can move extremely quickly and can have a major advantage for cross-border settlement.
The winner changes when the payment journey changes.
A USDC transfer that starts and ends on blockchain infrastructure can be very fast.
A USDC payment that starts as rand and must end as rand may require enough additional steps to lose that advantage.
For South Africans, the better question is not:
“Which technology is faster?”
It is:
“What form of money does the recipient actually need, and where does the payment need to end?”
That is where the real comparison begins.
For broader context, see Cryptocurrency in South Africa. If you are specifically looking at acquiring USDC, see How to Buy USDC in South Africa.
For the compliance side, read Crypto Regulation in South Africa. For the latest tax implications of buying, holding and trading crypto, see SARS's New Crypto Tax Guide.